Quick Answer: Silicon Valley Bank and Signature Bank collapsed in March 2023 due to a combination of concentrated depositor bases, heavy investment in long-term bonds during a period of rising interest rates, and rapid bank runs by panicked depositors. The FDIC stepped in and guaranteed all deposits, including those above the $250,000 insurance limit. Customers of failed banks kept the same routing numbers. If you need to order new business checks after switching to a new bank, see how to order checks online.


-
 Contact Us
-
 Re order
-
 Log in
-
 Cart 0
You have no items in your shopping cart.
The Collapse Of Two US Banks: What Happened, and What Now?
Checkomatic business checks for businesses opening new accounts after a bank change, with all security features standard on every order.
We tend to view banks as secure locations where our money is safeguarded behind locked doors, steel bars, and digital firewalls, but the reality is that they are inherently unstable. Banks make a profit by accepting deposits, lending money to borrowers, and earning interest on those loans. Therefore, the recent collapses of Silicon Valley Bank and Signature Bank are not entirely unexpected given the nature of the banking business model.
The rapid collapse of Silicon Valley Bank and Signature Bank resembled a classic bank-run scenario, where a large number of depositors withdraw their funds simultaneously. The speed of their failure was so astonishing that it could serve as a textbook example. These two banks' failures rank among the three largest in American banking history, after the 2008 downfall of Washington Mutual.
On Sunday night, regulators took sudden action to shut down Signature Bank to avoid a potential crisis in the wider banking system. The abrupt closures of these banks have caused significant disruption in the tech industry, as well as in Washington and Wall Street. As a result, the stocks of several regional banks experienced a sharp decline on Monday. However, on Tuesday, there was a brief moment of relief as bank stocks partially recovered their losses in early trading, easing some of the panics.
Why did Silicon Valley Bank fail?
Silicon Valley Bank was a major provider of banking services to the US technology and life-science industries, as well as to venture capital firms. Like many of its competitors, it invested most of its deposits in long-term debt, such as Treasury bonds, which promised steady but modest returns.
However, this strategy proved shortsighted when interest rates started to rise due to rapid inflation. Additionally, the bank's concentration in the tech industry made it vulnerable to start-up funding fluctuations, leading to increased account withdrawals from clients.
The bank's reliance on uninsured depositors further exacerbated its financial difficulties, as it was forced to sell investments at a significant discount to meet customer demands. Silicon Valley Bank's eventual collapse triggered a bank run by panicked start-ups, resulting in its takeover by the Federal Deposit Insurance Corporation (FDIC) and the control of $175 billion in customer deposits.
The FDIC's responsibility is to maintain stability and public confidence in the US financial system. The failure of Silicon Valley Bank is the largest since the 2008 financial crisis, and some experts believe that regulatory measures like the Dodd-Frank package could have prevented such a collapse if they had not been reduced.
Why did Signature Bank fail?
On Sunday, regulators closed Signature Bank to prevent a financial crisis in the wider system, just two days after Silicon Valley Bank was taken over by the FDIC. Signature Bank had deposits of under $100 billion across 40 branches in the country and had clients that included people associated with the Trump Organization.
The bank decided to take deposits of crypto assets in 2018, a decision that proved fateful after the FTX cryptocurrency exchange collapsed. Most of the bank's clients had more than $250,000 in their accounts, and almost 90% of Signature Bank's roughly $88 billion in deposits were uninsured at the end of last year. As Silicon Valley Bank's issues began to spread, Signature Bank's customers panicked and withdrew their deposits, causing the bank's stock and that of some of its peers to plummet.
What have regulators done so far?
The fallout from the collapse of two banks in three days has prompted regulators to rush to contain it, causing a swift re-evaluation of the Fed's interest rate increases. Before the banks' collapse over the weekend, the Fed had been expected to increase rates by half a point at its upcoming meeting on March 21-22.
On Sunday, regulators announced the closure of Signature and reassured depositors of both Signature and Silicon Valley Bank that they would be fully compensated and have access to their money by Monday. President Biden also assured the public on Monday that the financial system was stable and that their deposits were secure.
Treasury Secretary Janet L. Yellen acknowledged the situation on Sunday and reassured the public that the broader American banking system was safe and well-capitalized. However, she also acknowledged that many small businesses had funds tied up at the bank and suggested that an acquisition of Silicon Valley Bank could be a possible solution.
The F.D.I.C. started an auction for Silicon Valley Bank on Saturday, which was set to wrap up on Sunday. On Sunday, the F.D.I.C. invoked a systemic risk exception, allowing the government to pay back uninsured depositors to prevent dire consequences for the economy or financial instability.
Additionally, on Sunday, the Fed announced that it would establish an emergency lending program, with Treasury approval, to provide extra funding to eligible banks and ensure that all depositors' needs were met.
Are other banks at risk?
The failures of Silicon Valley Bank and Signature Bank highlighted the challenges faced by smaller banks that focus on specialized industries and are more susceptible to bank runs than larger banks. The main concern is that the failure of one bank could trigger fear in customers of other banks, leading to a domino effect of withdrawals.
Despite their relatively small size compared to larger banks like JPMorgan Chase, the sudden collapse of Silicon Valley Bank and Signature Bank caused shares of U.S. regional banks to plummet on Monday. In contrast, bigger banks like Citigroup and Wells Fargo were less affected, with the KBW bank index falling 10 percent and erasing nearly $200 billion from the aggregate value of the banks in the index.
Smaller banks rushed to reassure their customers that they were financially stable. First Republic Bank took the biggest hit, falling 60 percent, followed by Western Alliance in Arizona, which tumbled 45 percent, and KeyCorp, Comerica, and Zions Bancorp, which all experienced significant declines.
What happens next for people who had ties to Signature Bank and Silicon Valley Bank?
According to federal officials, customers of Silicon Valley Bank (SVB) will have full access to their deposits, including accounts that held more than the FDIC insurance limit of $250,000. The majority of accounts at SVB held more than that amount, totaling $175 billion in customer deposits.
This move essentially guarantees these deposits. The officials also stated that deposits at Signature Bank will be backstopped, and operations at both banks resumed on Monday, allowing account holders access to their funds.
This means that companies relying on cash deposits at SVB for their daily operations, such as making payroll, can carry on as normal. However, the FDIC warns that shareholders and some debtholders will not be protected and senior management has been removed from their jobs.
What happens next for everybody else?
Federal officials are taking steps to prevent a potential "contagion" from spreading to other banks, assuring customers that their deposits will be safe. President Biden confirmed this in a statement on Monday, stating that "the banking system is safe". The Federal Reserve Board has made funding available to other banks to help bolster their cash reserves and prevent a possible bank run. Despite these measures, the stock market experienced significant volatility on Monday, with government bonds becoming a popular haven for investors.
The drop in the 2-year Treasury yield, which reflects investor expectations about interest rates, has been particularly pronounced, falling from just over 5% to just under 4% since the middle of last week. This comes ahead of a Federal Reserve meeting next week, during which the Fed will decide whether or not to raise its benchmark interest rate again.
The Fed's rapid interest rate increases in recent months have helped to control inflation, but have also had a negative impact on bond holdings such as those invested in by SVB, which contributed to its collapse last week.
Prior to the collapse of SVB, the markets had expected the Fed to raise interest rates by half a percentage point at its March meeting. However, with pressure on the Fed to ease up on these increases, these expectations have since receded.
Understanding FDIC Coverage: What the $250,000 Limit Means for Business Accounts
The SVB and Signature Bank collapses put a spotlight on FDIC insurance and what it actually covers. Here is a plain-language summary of how the coverage works for business depositors.
The Federal Deposit Insurance Corporation (FDIC) insures deposits at member banks up to $250,000 per depositor, per bank, per ownership category. For a business with a standard checking account, this means up to $250,000 is insured. For many of the companies that banked with SVB, this limit was far below their actual account balances, which is why the FDIC's decision to invoke the systemic risk exception and cover all deposits regardless of amount was significant.
Key points for business account holders:
- $250,000 is the standard limit per depositor per bank for FDIC-insured accounts.
- Business accounts are separate from personal accounts at the same bank, each eligible for their own $250,000 coverage.
- Multiple ownership categories (sole proprietor, LLC, corporation) may qualify for separate coverage limits at the same bank.
- Uninsured deposits are those above the coverage limit. In the SVB case, roughly 90 percent of deposits were uninsured before the government backstop was announced.
For a detailed explanation of how bank routing numbers work and what happens to your account details when a bank changes ownership, see ABA routing numbers explained and ABA routing number guide: where to find it and how it works.
Routing Numbers, Account Numbers, and What Changes When a Bank Fails
One of the most practical concerns for businesses after a bank failure is whether their routing number and account number change. For SVB and Signature Bank customers, the answer was that routing numbers stayed the same in the immediate aftermath because the FDIC took over operations and continued processing transactions. However, for customers who ultimately moved to a new bank, new routing and account numbers were assigned.
Do You Need New Checks When You Switch Banks?
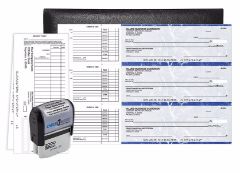
Yes. If you open an account at a new bank, your new account will have a different ABA routing number and a different account number. Your existing business checks are printed with the old bank's routing number in the MICR line at the bottom. Checks with the old routing number will not route correctly to your new account. You will need to order new check stock pre-printed with your new bank's routing number and your new account number before you can write checks from the new account.
What to have ready before ordering new checks: Your new bank's ABA routing number (from the online banking portal or a bank-issued document), your new account number, your business name and address exactly as they appear on the new account, and your starting check number. Do not use the routing number from a deposit slip, as some banks use different routing numbers for different transaction types. See ABA routing number guide: where to find it and how it works.
For everything you need to know about ordering business checks for a new bank account, including what information to gather, which format to choose, and how long shipping takes, see how to order checks online and bank checks: ordering, usage, and cost guide.
Where to Order Business Checks after Creating a Checking Account with a New Bank
For many customers of these banks, the sudden closure has created a headache when it comes to finding new banking options. One of the most important concerns for these customers is whether they will need to obtain new routing numbers for their accounts. The good news is that both Signature Bank and Silicon Valley Bank have made it clear that customers will not need to obtain new routing numbers.
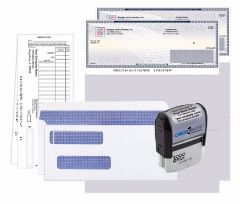
However, customers who need to order new checks will need to find a reliable resource for doing so. This is where Checkomatic.com comes in. Checkomatic.com is a leading provider of high-quality checks that are custom-designed to meet the needs of individual customers. With a wide range of options available, including business checks, personal checks, and more, Checkomatic.com is the go-to resource for anyone who needs to order new checks.
Customers who are looking for a reliable and affordable way to order new checks can turn to Checkomatic.com for help. With a user-friendly website and a wide selection of high-quality check designs, Checkomatic.com makes it easy for customers to order the checks they need quickly and easily. Plus, with fast shipping and excellent customer service, customers can rest assured that they will get the support they need when they need it.
In conclusion, the closure of Signature Bank and Silicon Valley Bank has left many customers looking for new banking solutions. While customers will not need to obtain new routing numbers, they will need to find a reliable resource for ordering new checks. Checkomatic.com is the perfect resource for anyone who needs to order new checks quickly and easily. With a wide selection of high-quality check designs and excellent customer service, Checkomatic.com is the go-to source for all of your check needs.
Check Security When Opening a New Bank Account
ABA-compliant security features on every Checkomatic business check, protecting your new bank account checks from fraud and washing.
Opening a new bank account and ordering a new supply of checks is a moment of vulnerability from a check fraud standpoint. Fraudsters target businesses that have recently changed banking details, because a new check supply means the business's positive pay records at the new bank are empty, and any presented check will be processed without a match to verify against.
Every Checkomatic business check includes six ABA-compliant security features at the base price: chemical-reactive paper, microprint signature line, void pantograph, heat-sensitive ink, coin-reactive ink, and true watermark. These protect your new checks from washing and counterfeiting from the first sheet printed. For the complete guide to check fraud prevention, see are business checks safe: security features that actually matter.
Shop New and Custom Business Checks with Checkomatic
Visit Checkomatic.com to shop Business Checks and follow us on Facebook, LinkedIn, and YouTube.
Shop Next-Day Business Checks with ChecksNextDay
When shopping with Checks Next Day, your order is guaranteed the next day for purchases placed before 3:00 pm, Monday through Friday, excluding legal holidays, unless otherwise noted online.
As always, please contact our customer service at 1-877-350-1224 or sales@checksnextday.com with any questions.
Visit ChecksNextDay.com to shop QuickBooks Checks, Computer Checks, or Manual Checks, and follow us on Facebook, LinkedIn, and YouTube.
What Customers Say About Checkomatic
All reviews below are published on checkomatic.com and reproduced verbatim. Source: checkomatic.com/quickbooks-starter-pack-product, 4.5 stars from 166 verified reviews.
"Been with them for 15 years. Always reliable, always good quality, good service. What more can you ask for?"
ATV Inc. | ★★★★★ 5/5 | April 5, 2024 | Source: checkomatic.com/quickbooks-starter-pack-product
"First time ordering and I am super impressed with the quality of the checks. No issues with delivery. I will be ordering again!"
TClinton | ★★★★★ 5/5 | April 9, 2025 | Source: checkomatic.com/quickbooks-starter-pack-product
"We use CheckoMatic for all of our check needs! They have great prices and we receive our products in a timely manner!"
CG's Tax Service | ★★★★★ 5/5 | September 18, 2024 | Source: checkomatic.com/quickbooks-starter-pack-product
"I got 500 checks for less than half of what the bank wanted for 200!"
VVA Voucher Checks (Vietnam Veterans of America) | ★★★★★ 5/5 | July 6, 2024 | Source: checkomatic.com/quickbooks-starter-pack-product
"ASJ Wilson Construction has been a client of checkomatic for some years now and they've never disappointed this company. Thank you checkomatic for all that you do."
ASJ Wilson Construction | ★★★★★ 5/5 | June 6, 2024 | Source: checkomatic.com/quickbooks-starter-pack-product
"Affordable and efficient. My go-to business check printer."
Doe | ★★★★★ 5/5 | January 24, 2025 | Source: checkomatic.com/quickbooks-starter-pack-product
Accepted by the world’s leading banks